Otong Michael Favour

Category: Legal Insight

  • Munyanga Development Limited v Uganda Revenue AuthorityTAT Application No. 73 of 2026 | [2026] UGTAT 43

    Munyanga Development Limited v Uganda Revenue AuthorityTAT Application No. 73 of 2026 | [2026] UGTAT 43

    Background

    The case concerned the statutory time within which the Uganda Revenue Authority (URA) is required to make and serve an objection decision following a taxpayer’s objection to a tax assessment.Munyanga Development Limited had lodged an objection but URA did not serve an objection decision within the statutory 90-day period. Upon expiry of the period, the taxpayer exercised its statutory right to elect to treat the objection as allowed.

    URA subsequently issued an objection decision and sought to maintain the tax assessment. The taxpayer challenged the validity of URA’s subsequent decision before the Tax Appeals Tribunal.

    Issue

    The central question was whether URA retained jurisdiction to issue an objection decision after the statutory 90-day period had expired and the taxpayer had validly elected to treat its objection as allowed.

    Decision

    The Tribunal found in favour of the taxpayer. It held that once the statutory period had expired without an objection decision being served, a valid election by the taxpayer to treat the objection as allowed took effect automatically.

    Consequently, URA became functus officio and had no further jurisdiction to issue an objection decision in respect of the objection. The subsequent decision by URA was therefore void.

    The Tribunal also rejected the argument that the general rules of computation under the Interpretation Act could be used to extend the specific statutory timeline governing tax objections.

    Significance

    The decision is an important reminder that statutory tax timelines are not merely procedural formalities. They impose obligations on both taxpayers and the revenue authority.

    For taxpayers, the case demonstrates the importance of closely monitoring the 90-day objection period and taking advantage of the statutory remedies available when URA fails to act within time.

    For URA, the decision reinforces that failure to comply with mandatory statutory timelines may result in the loss of jurisdiction to make a subsequent objection decision.

    Key takeaway:

    Once the statutory conditions for an election to treat an objection as allowed are satisfied, the taxpayer’s election takes effect by operation of law; URA cannot subsequently revive the matter by issuing a late objection decision.

  • The Art of Negotiation: Why Your Conflict Style Matters More Than You Think

    The Art of Negotiation: Why Your Conflict Style Matters More Than You Think

    Most of us have a default way of dealing with conflict.

    When a disagreement comes up at work, in business, in a family meeting, or even during a negotiation, some people immediately push to get their way. Others would rather keep quiet and avoid confrontation. Some give in quickly because they value peace. Others look for a middle ground.

    The interesting thing is that we often do this without thinking about it.

    Understanding your conflict style, and knowing when to move beyond it, is therefore one of the most underrated negotiation skills.

    Five Ways People Handle Conflict

    In 1974, researchers Kenneth Thomas and Ralph Kilmann developed a framework identifying five common approaches to conflict. The framework remains useful because it helps us understand something simple: people do not all approach disagreement in the same way.

    1. Competing: “I need to win.”

    The competing style treats conflict as a contest.

    The focus is on asserting your position, protecting your interests and getting the best possible outcome for yourself.

    There are situations where this is necessary. For example, if someone is taking advantage of you, breaching a contractual obligation or making an offer that is clearly unacceptable, being firm is important.

    But if every disagreement becomes a battle to be won, the cost can be high.

    You may win the argument and lose the relationship.

    This is particularly important in Uganda, where business and professional relationships are often closely connected. The person you negotiate against today may be a potential business partner, client, colleague or referral source tomorrow.

    2. Avoiding: “Let’s leave it for now.”

    Avoiding means stepping away from the conflict rather than confronting it immediately.

    Sometimes, this is good judgment.

    If emotions are extremely high, taking time before responding can prevent a small disagreement from becoming a serious dispute. Similarly, not every disagreement deserves a lengthy negotiation.

    The problem comes when avoidance becomes your permanent strategy.

    A disagreement between business partners that is repeatedly ignored does not necessarily disappear. An employee who is unhappy but never speaks up may eventually resign. A family disagreement over property may remain quiet for years before becoming a much bigger succession dispute.

    Silence can preserve peace temporarily without necessarily creating peace permanently.

    3. Accommodating: “Let me give in.”

    The accommodating style prioritises the other person’s needs, often to preserve harmony.

    In Uganda, where relationships, respect for elders and maintaining social harmony can carry significant weight, this approach can sometimes be very useful.

    There are moments when giving way is simply the wiser choice.

    But constantly giving in has consequences.

    If you always accept the lower share, remain silent about unfair treatment or agree to terms you are uncomfortable with just to avoid an argument, resentment can eventually build.

    Peace at any price is not always peace.

    4. Compromising: “Let’s meet halfway.”

    Compromise is probably one of the most familiar approaches to conflict.

    Each side gives something up and both parties move towards the middle.

    It is useful when time is limited, the issue is relatively straightforward or neither party can achieve everything they want.

    But compromise has a weakness: splitting the difference does not always solve the real problem.

    Imagine two business partners arguing over whether a particular expense should be UGX 10 million or UGX 20 million. Agreeing on UGX 15 million may look fair. But what if the real disagreement is about whether the expense is necessary at all?

    Sometimes, the best solution is not halfway between two positions. It is finding out why the parties are taking those positions in the first place.

    5. Collaborating: “Let’s understand what is really important.”

    Collaboration goes deeper.

    Instead of concentrating only on what each side is demanding, the parties try to understand the interests behind those demands.

    For example, a landlord may insist on a particular rent because they need predictable income. A tenant may resist because their business is struggling with cash flow.

    The stated positions are:

    Landlord: “I need the rent increased.”

    Tenant: “I cannot afford the increase.”

    But the underlying interests may provide more room for negotiation.

    Perhaps the tenant can accept an increase if it is phased over several months. Perhaps the landlord would accept a smaller increase in exchange for a longer lease.

    That is the power of collaborative negotiation: it searches for solutions that were not visible when both sides were simply defending their positions.

    It usually takes more time and effort, but it can produce agreements that are stronger and more sustainable.

    There Is No Single “Right” Conflict Style

    It is tempting to conclude that collaboration is always the best approach.

    It isn’t.

    The real skill is flexibility.

    A good negotiator knows when to change approach.

    Compete when you need to protect an important interest or firmly establish a boundary.

    Accommodate when preserving an important relationship matters more than winning a particular point.

    Avoid when emotions are too high for a productive conversation or when the issue is simply not worth engaging.

    Compromise when a practical solution is more important than getting everything you want.

    Collaborate when the relationship matters, the issue is complex and there may be opportunities for both sides to gain.

    The mistake is not having a particular conflict style.

    The mistake is using the same style in every situation.

  • A Practical Guide to Tax Planning for Small Businesses, SMEs, and Startups in Uganda

    A Practical Guide to Tax Planning for Small Businesses, SMEs, and Startups in Uganda

    In today’s increasingly regulated business environment, taxation is no longer merely a statutory obligation; it has become a critical component of sound corporate governance and strategic business management. Every business, regardless of its size or industry, operates within a legal framework that requires it to account for its tax obligations accurately and in a timely manner. Unfortunately, many businesses in Uganda continue to approach taxation reactively, giving attention to compliance only after receiving a notice of audit, an additional assessment, or an enforcement action from the Uganda Revenue Authority (URA). By that stage, what could have been prevented through proper planning often becomes an expensive exercise in dispute resolution.

    Tax planning should never be mistaken for tax evasion.

    While tax evasion involves deliberately concealing income, falsifying records, or misrepresenting transactions to reduce tax liability, tax planning is the lawful arrangement of one’s financial and business affairs to ensure that taxes are managed efficiently within the confines of the law. It is an exercise in foresight rather than avoidance. Businesses that invest in proper tax planning are not seeking to escape their tax obligations; rather, they seek to understand them, comply with them, and organise their operations in a manner that promotes efficiency while minimising unnecessary tax risks.

    Understanding Uganda’s Tax System

    One of the greatest misconceptions among business owners is that tax planning is only relevant to large corporations with complex financial structures. This assumption could not be further from the truth. Whether one operates a small retail shop, a growing technology startup, a professional services firm, or a multinational enterprise, tax planning remains equally important. Every business decision from how a company is incorporated to how employees are remunerated, assets are acquired, contracts are drafted, or investments are financed has tax implications. Consequently, tax considerations should be integrated into business decision-making from the very beginning rather than being treated as an afterthought.

    Maintain Accurate and Reliable Financial Records.

    The foundation of effective tax planning lies in maintaining accurate and reliable financial records. The Income Tax Act and other tax legislation place significant emphasis on documentation. During a tax audit, the issue is rarely whether a business believes it incurred an expense; the question is whether it can demonstrate that expense through proper records. Sales invoices, purchase invoices, contracts, payroll records, bank statements, import documentation, inventory records, and accounting books collectively form the evidence upon which tax compliance is assessed. Businesses that neglect proper record keeping expose themselves to unnecessary adjustments, disallowed deductions, penalties, and prolonged disputes with the tax authority.

    Timely compliance

    Timely compliance is another indispensable aspect of tax planning. Filing returns and paying taxes within the prescribed statutory deadlines may appear routine, yet failure to do so often attracts interest and penalties that exceed the original tax liability. These avoidable costs not only strain cash flow but may also affect a business’s reputation and its ability to secure financing or attract investors. Compliance should therefore not be viewed merely as an administrative obligation but as an investment in the financial health and credibility of the enterprise.

    Appreciate tax legislation

    Businesses should also appreciate that tax legislation is dynamic. Amendments to tax laws are introduced almost every financial year, altering tax rates, introducing new compliance obligations, revising available exemptions, or modifying reporting requirements. A tax strategy that was fully compliant several years ago may no longer reflect the current legal position. It is therefore prudent for businesses to review their tax positions periodically, monitor legislative developments, and seek professional advice whenever significant legal changes occur. Remaining informed enables businesses to adjust proactively rather than reacting after non-compliance has already occurred.

    Separation of personal and business finances.

    Equally important is the separation of personal and business finances. This remains one of the most common weaknesses observed among owner-managed enterprises. When personal expenditures are routinely paid from business accounts without proper documentation or accounting treatment, distinguishing legitimate business expenses from private consumption becomes increasingly difficult. Such practices complicate financial reporting and create unnecessary challenges during tax audits. Maintaining separate bank accounts, implementing sound accounting controls, and documenting every transaction are simple yet effective measures that significantly reduce tax exposure.

    Proper Identification and Utilisation of Lawful Tax Incentives.

    Another area that deserves careful attention is the proper identification and utilisation of lawful tax incentives. Uganda’s tax system contains various incentives designed to promote investment, industrialisation, exports, manufacturing, and other sectors considered vital to national economic development. Yet many businesses fail to benefit from these incentives, not because they are ineligible, but because they are unaware of their existence or seek professional advice only after major investment decisions have already been made. Tax planning therefore involves more than avoiding penalties; it also involves recognising legitimate opportunities created by law to improve business efficiency and encourage growth.

    Conducting Periodic Internal Tax Reviews.

    Perhaps the most overlooked component of tax planning is conducting periodic internal tax reviews. Many businesses assume that because returns have been filed, compliance has been achieved. In reality, filing a return does not necessarily mean that it has been completed correctly. Errors in PAYE calculations, VAT treatment, withholding tax obligations, deductible expenses, or corporate income tax computations may remain undiscovered until a URA audit reveals them. Internal tax reviews provide businesses with an opportunity to identify and correct such issues voluntarily before they develop into costly disputes. Preventive compliance is invariably less expensive than corrective enforcement.

    Consult Tax Professionals

    Professional advice also plays an essential role in effective tax planning. Businesses frequently consult tax professionals only after a problem has arisen, by which time available options may already be limited. Seeking legal and tax advice before undertaking significant transactions such as business acquisitions, corporate restructuring, financing arrangements, cross-border transactions, or major capital investments allows potential tax consequences to be identified and addressed at the planning stage. Early intervention often results in better structuring, reduced risks, and greater certainty for all parties involved.

    NOTE

    Ultimately, tax planning should not be viewed as an annual exercise undertaken shortly before filing returns or responding to a URA notice. It should be embedded within the broader governance framework of every business. Organisations that cultivate a culture of compliance, maintain accurate records, review their tax affairs regularly, and seek timely professional guidance are better equipped to withstand regulatory scrutiny and pursue sustainable growth. They spend less time resolving avoidable disputes and more time concentrating on innovation, expansion, and value creation.

    The Uganda Revenue Authority continues to strengthen its compliance and enforcement mechanisms through digital systems, data analytics, and improved information sharing across government institutions. As a result, businesses should expect tax administration to become increasingly sophisticated in the years ahead. The question, therefore, is not whether a business will one day come under the scrutiny of the tax authority, but whether it will be adequately prepared when that day arrives.

    The most effective tax strategy is not one developed after URA has issued an assessment or commenced an audit. It is the strategy implemented long before any questions are asked. Businesses that embrace proactive tax planning position themselves not merely to comply with the law but to operate more efficiently, protect their financial resources, and build organisations capable of achieving long-term success.

    Sound tax planning is, therefore, far more than a compliance exercise. It is a hallmark of responsible corporate governance, prudent financial management, and sustainable business leadership.

  • Taxation of Agricultural Companies in Uganda: A Practical Guide for Agribusiness Investors

    Taxation of Agricultural Companies in Uganda: A Practical Guide for Agribusiness Investors

    Introduction

    Agriculture remains the cornerstone of Uganda’s economy, accounting for a substantial share of employment, exports, and rural livelihoods. In recent years, the sector has witnessed increased commercialisation, with investors, cooperatives, and farming enterprises adopting corporate structures to facilitate growth, access financing, and improve governance.

    Whether engaged in coffee cultivation, livestock farming, horticulture, grain production, aquaculture, or agro-processing, agricultural companies operating in Uganda are subject to a range of tax obligations. At the same time, the law provides several incentives intended to encourage investment in agriculture and support value addition within the sector.

    Despite these incentives, many agribusinesses face compliance challenges arising from inadequate record keeping, misunderstanding of tax obligations, worker misclassification, and improper treatment of agricultural products for Value Added Tax (VAT) purposes. Such challenges often result in penalties, interest, and disputes with the Uganda Revenue Authority (URA).

    This article provides a practical overview of the taxation of agricultural companies in Uganda, highlights available tax incentives, and outlines best practices for establishing and operating a tax-compliant agribusiness.

    Establishing an Agricultural Company: Tax Considerations from the Start

    Tax compliance begins long before a business generates its first sale. Once an agricultural enterprise is incorporated, one of the immediate requirements is obtaining a Tax Identification Number (TIN) from the Uganda Revenue Authority. Although often viewed as a procedural formality, tax registration creates ongoing obligations that directors and investors must understand from the outset.

    Many agricultural ventures incur substantial expenditure during their establishment phase. Costs associated with land preparation, irrigation infrastructure, seedlings, farm buildings, machinery, and labour can be significant, while revenue generation may take months or even years. Nevertheless, tax filing obligations continue to apply regardless of whether the company has begun generating income.

    Integrating tax planning into the early stages of business development helps ensure compliance while positioning the company to take advantage of available tax incentives. Businesses that neglect tax compliance during their formative years often encounter avoidable liabilities when they eventually become profitable or seek external investment.

    Corporation Income Tax and Agricultural Businesses

    Agricultural companies operating in Uganda are generally subject to Corporation Income Tax on their chargeable income. Chargeable income is calculated by deducting allowable business expenses from gross income earned during the year.

    Agriculture differs from many other sectors because substantial investment is often required before meaningful income is realised. A coffee plantation, for example, may require several years of investment in land preparation, seedlings, irrigation systems, labour, fertilizers, and farm management before reaching commercial production.

    Consider a company that establishes a 100-acre coffee plantation. During the first three years, the company incurs significant operational costs but generates little or no revenue because the coffee trees have not matured. In such circumstances, the company may report tax losses rather than taxable profits. These losses may have important tax implications and should be properly documented and recorded.

    A common misconception among business owners is that companies operating at a loss are not required to file tax returns. This is incorrect. Annual income tax returns must generally be filed regardless of whether the company has generated profits, incurred losses, or remained dormant.

    Proper accounting records are therefore essential. Every expenditure relating to farm operations should be supported by invoices, receipts, contracts, payroll records, or other relevant documentation. During a tax audit, the burden often falls upon the taxpayer to demonstrate that claimed deductions are legitimate and directly connected to the production of income.

    Managing Employment Taxes in Agricultural Operations

    Agriculture is a labour-intensive industry. Depending on the scale of operations, an agricultural company may employ farm managers, supervisors, machine operators, technical specialists, administrative staff, seasonal workers, and casual labourers.

    Under Uganda’s tax laws, employers are required to account for Pay As You Earn (PAYE) on employment income paid to employees. While this principle appears straightforward, difficulties often arise when businesses engage casual or seasonal workers.

    The distinction between an employee and an independent contractor is particularly important because different tax obligations arise depending on the nature of the relationship. Tax authorities typically examine factors such as the degree of control exercised by the employer, working hours, provision of tools and equipment, supervision, and the worker’s economic independence.

    Where a farm worker reports to a supervisor, works fixed hours, uses tools supplied by the company, and performs duties under direct management control, the relationship is likely to be classified as employment for tax purposes. Conversely, an independent contractor generally determines how work is performed and bears responsibility for the resources used in delivering the agreed services.

    Misclassification of workers can expose agricultural companies to assessments for unpaid PAYE, interest, and penalties. Businesses should therefore establish clear employment policies and maintain proper payroll records to support compliance.

    Value Added Tax and Agricultural Products

    The VAT treatment of agricultural products is one of the most frequently misunderstood aspects of agricultural taxation.

    Ugandan law generally exempts the supply of certain unprocessed agricultural products from VAT. This policy is intended to support primary agricultural production and reduce costs within the agricultural sector.

    However, determining whether a product qualifies as “unprocessed” is not always straightforward. Activities such as sorting, drying, chilling, freezing, cleaning, husking, and bulk packaging may still fall within the scope of unprocessed agricultural products depending on the circumstances.

    The position changes significantly where substantial processing or value addition occurs. For example, raw coffee beans may qualify as an exempt agricultural product, while roasted coffee, packaged consumer coffee products, or processed coffee extracts may constitute taxable supplies.

    This distinction becomes increasingly important as businesses move up the value chain. An enterprise that begins as a primary producer may later establish processing facilities and become subject to VAT registration requirements once statutory thresholds are met.

    Accordingly, agricultural businesses should evaluate the tax implications of any value-addition activities before implementation to avoid unexpected tax liabilities.

    Withholding Tax Obligations in Agricultural Businesses

    Agricultural companies frequently engage external service providers, including accountants, lawyers, agronomists, engineers, veterinarians, consultants, and contractors. Payments made to such professionals may attract withholding tax obligations under the Income Tax Act.

    One of the most common findings during tax audits is the failure to withhold tax where required. In many cases, businesses assume that tax compliance is the responsibility of the service provider. However, the law places specific obligations on the payer.

    Failure to withhold tax can result in the company becoming liable for the unpaid tax together with interest and penalties. Consequently, agricultural businesses should establish procedures to review professional service payments before disbursement and confirm whether withholding obligations apply.

    National Social Security Fund (NSSF) Compliance

    In addition to tax obligations, agricultural companies must comply with social security requirements under the National Social Security Fund framework. Employers are generally required to register eligible employees and remit statutory contributions within prescribed timelines.

    This obligation applies not only to administrative staff and managers but may also extend to workers engaged directly in agricultural operations where an employment relationship exists.

    Businesses that maintain formal payroll systems and employee records are generally better positioned to comply with NSSF obligations than those relying exclusively on informal labour arrangements.

    Tax Incentives Available to Agricultural Companies

    Uganda’s tax framework contains several incentives intended to encourage agricultural investment and improve productivity within the sector.

    These incentives include VAT exemptions applicable to certain unprocessed agricultural products, favourable treatment for qualifying agricultural inputs, customs relief on selected agricultural machinery and equipment, and deductions available for qualifying business expenditure.

    Agricultural businesses may also benefit from capital allowances, wear-and-tear deductions, and the ability to carry forward tax losses in accordance with applicable legislation.

    Investors should conduct periodic reviews of their operations to ensure that available incentives are identified and properly utilised.

    Record Keeping and Tax Audit Preparedness

    One of the most overlooked aspects of agricultural tax compliance is record management. Yet it is often the decisive factor during a tax audit.

    Agricultural companies should maintain comprehensive records relating to:

    • Farm sales and produce deliveries;
    • Purchase invoices and receipts;
    • Payroll records;
    • Casual labour registers;
    • Asset registers;
    • Machinery maintenance records;
    • Land ownership or lease documentation;
    • Input purchases such as fertilizers, pesticides, and seedlings;
    • Contracts with suppliers and service providers.

    Well-maintained records not only support tax compliance but also improve access to financing, strengthen corporate governance, and facilitate business growth.

    Common Tax Mistakes Made by Agricultural Companies

    Several recurring compliance issues continue to affect agricultural businesses in Uganda.

    These include failing to file tax returns because the business has made losses, misclassifying workers, neglecting withholding tax obligations, misunderstanding VAT treatment of processed products, and maintaining inadequate accounting records.

    Most of these challenges can be avoided through proper planning, regular tax reviews, and professional advice.

    Best Practices for Structuring a Tax-Compliant Agricultural Company

    Successful agricultural businesses view tax compliance as part of their overall business strategy rather than a regulatory burden.

    Investors should establish proper accounting systems from the outset, conduct periodic tax health checks, maintain detailed records, review labour arrangements regularly, and seek professional advice before embarking on major investments or value-addition projects.

    Proactive tax planning not only reduces compliance risks but also enhances profitability by ensuring that available incentives and deductions are fully utilised.

    Coffee Farming and Taxation in Uganda: Special Considerations for Investors

    Coffee remains Uganda’s leading agricultural export and continues to attract significant domestic and foreign investment. Investors entering the coffee sector should pay particular attention to the distinction between primary production and processing activities.

    The tax treatment of green coffee beans may differ substantially from that of roasted, packaged, or otherwise processed coffee products. Similarly, businesses involved in coffee exports should evaluate the implications of VAT, customs procedures, and available export-related incentives.

    Given the long maturation period associated with coffee farming, investors should also pay close attention to tax planning, loss utilisation, capital allowances, and record-keeping requirements during the early years of operation.

    Conclusion

    Agriculture presents substantial opportunities for investment and economic growth in Uganda. However, the benefits of operating within the sector can only be fully realised where businesses understand and comply with applicable tax obligations.

    Corporation Income Tax, PAYE, VAT, withholding tax, and NSSF requirements all play an important role in the regulatory framework governing agricultural enterprises. At the same time, various incentives exist to support investment, mechanisation, and value addition.

    Agricultural companies that adopt strong governance practices, maintain proper records, and engage in proactive tax planning are better positioned to achieve sustainable growth while minimising regulatory risk.

    Disclaimer: This article is intended for general informational purposes only and does not constitute legal or tax advice. Businesses should seek professional advice tailored to their specific circumstances before making decisions based on tax legislation or administrative practice.
  • The New Uganda Income Tax Laws 2026: Who Pays More, Who Pays Less, and What It Means for You

    The New Uganda Income Tax Laws 2026: Who Pays More, Who Pays Less, and What It Means for You

    The new PAYE threshold

    The Income Tax (Amendment) Act, 2026 represents a significant step in Uganda’s ongoing efforts to balance revenue mobilisation, taxpayer protection, and economic growth. While Government initially proposed several aggressive tax measures aimed at widening the tax base, Parliament ultimately moderated many of these proposals, resulting in a more balanced legislative outcome.

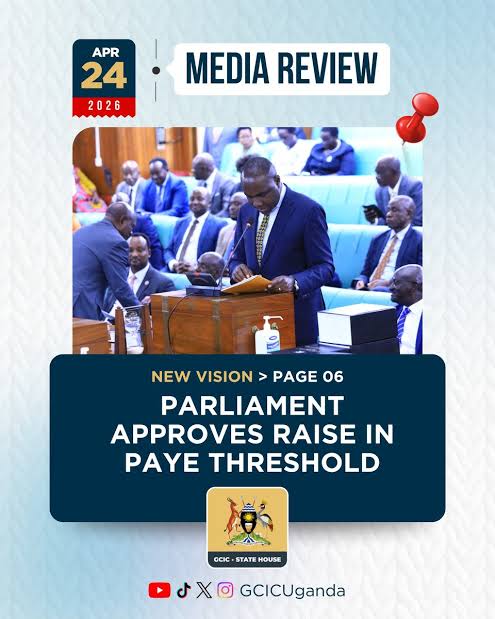
    One of the most notable effects of the amendments is the increase in the Pay As You Earn (PAYE) tax-free threshold from UGX 235,000 to UGX 335,000 per month. This reform provides relief to low-income earners by increasing disposable income and reducing the tax burden on vulnerable households. It further promotes the principle of equity in taxation by ensuring that individuals with lower earnings retain a larger proportion of their income.

    The amendments also enhance certainty in the taxation of digital transactions through the expansion of the definition of royalties to include software-related payments. This clarification strengthens tax administration and reduces ambiguity in the treatment of cross-border software transactions. However, it may increase the cost of acquiring software and digital services from non-resident providers due to the application of withholding tax obligations.

    Equally important is Parliament’s rejection of the proposed Alternative Minimum Tax on loss-making businesses and the proposed taxation of gains arising from the disposal of non-business assets. These decisions preserve fundamental principles of income taxation by ensuring that tax liability remains linked to actual income or gains rather than turnover or ordinary personal transactions. The rejection of these proposals is likely to enhance investor confidence and support business growth, particularly in sectors characterised by long investment cycles and delayed profitability.

    Overall, the Income Tax (Amendment) Act, 2026 demonstrates Parliament’s commitment to achieving a fair balance between increasing domestic revenue and maintaining an attractive environment for investment and economic development. The amendments are therefore expected to improve tax compliance, enhance certainty within the tax system, and provide targeted relief to taxpayers while safeguarding Uganda’s revenue interests.